
House Prices Are Stalling — Is the Next Drop Already Starting?
The latest market chatter is easy to skim past if you only read the headline. Prices are still rising in some areas, rents are still holding up in others, and there is always someone talking up “resilience”. But for landlords, developers and active investors, the more important point is simpler: the market is losing momentum, and that changes the maths.
Recent coverage from Property Industry Eye and The Guardian points in the same direction: house price growth has slowed, completions are taking longer, and the market is feeling less forgiving than the summer optimism suggested. That is not a crash story. It is more awkward than that. It is a warning that price growth is no longer doing the heavy lifting for you.
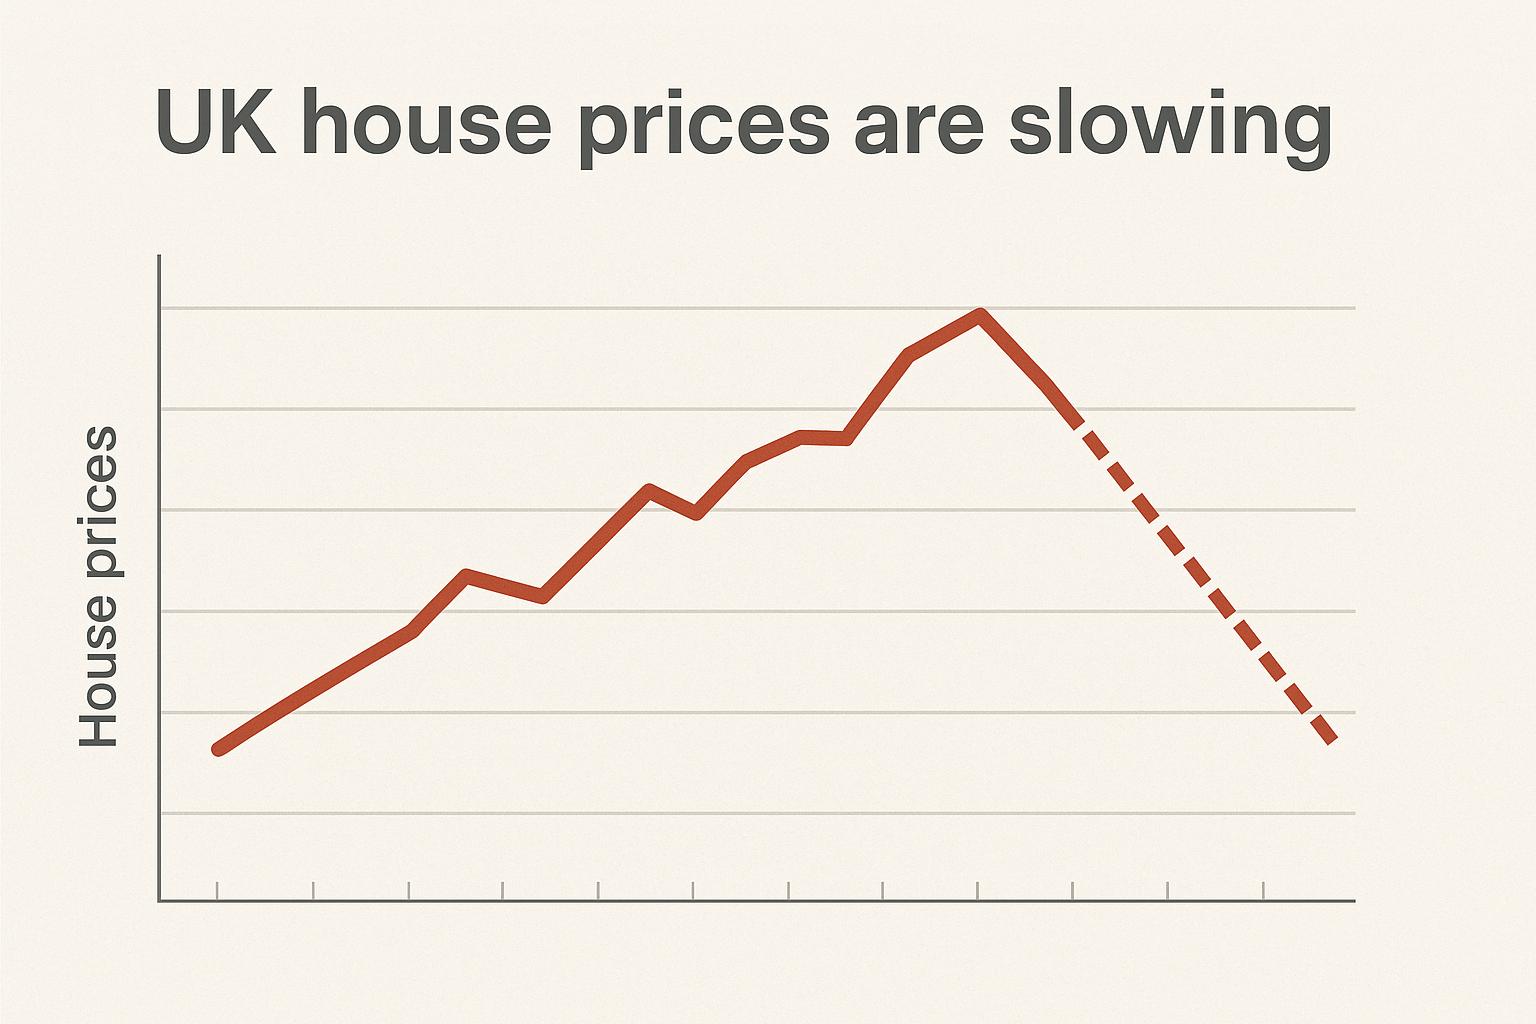
That matters because a lot of property strategies quietly depend on a generous exit. Developers rely on the completion valuation landing where they expected. Landlords rely on capital growth to make thin yields tolerable. Borrowers rely on a smooth refinance to release equity or clear bridging debt. When the market cools, all three assumptions can be tested at once.
The pressure does not show up evenly either. A market that looks only “flat” on paper can still create real stress in practice. If you bought on yesterday’s optimism, but your refinance valuation is measured against today’s more cautious comparables, the gap lands on you. That can mean lower leverage, more cash left in, a delayed refinance or a completely different exit plan.
Timing becomes part of the cost base as well. When sales take longer to complete, money stays tied up for longer. That affects interest costs, contractor exposure, voids and the true return on capital. In that sense, a slower market is not just about price direction. It is about friction, and friction is expensive.
For landlords, slowing house price growth is not automatically bad news. In a softer market, rental income matters more, and that can suit investors who are genuinely focused on cash flow rather than headline equity. But it only works if the yield is real, tenant demand is durable and the property still makes sense on sensible finance. If the deal only looked good because you were relying on future uplift, the slowdown exposes that quickly.
There is also an opportunity side to weaker sentiment, but it tends to reward discipline rather than bravado. Some owners get nervous when the market stops running for them, and that can create motivated sellers. Others simply become more realistic on price, especially if they need speed or certainty. For investors who can move decisively, that can improve buying opportunities. For everyone else, it is a reminder that a slower market rewards accurate underwriting far more than optimistic assumptions.
What matters now is price quality, not just price direction. Are the numbers supported by actual transactions, or by hopeful asking prices? Are agents seeing genuine demand, or just more listings? Are lenders comfortable with the asset type, EPC profile and exit route? A market can look stable while still becoming less forgiving underneath.
This is where valuation risk becomes very real. When momentum softens, down-valuations become more likely, especially where an asking price has drifted ahead of the evidence. Investors should treat valuation as a commercial checkpoint, not a formality. If your deal only works when the valuer shares your optimism, then you do not have a robust deal — you have a hope.
The right response is not panic. It is tighter appraisal. Stress-test the exit at a lower sale value and a slower sale period. Assume your refinance may take longer and may come back more conservatively than you hoped. Check whether the asset still works if rent growth is modest rather than heroic. And if you are buying now, use the softer mood to negotiate harder. In a slowing market, price is not the only thing you can improve. Terms, timing and certainty of execution all have value too.
The investors who tend to cope best in this environment are the ones who stop thinking like speculators. They do not need next quarter to be bullish. They need the deal to be bankable, lettable and saleable even if the market is merely average. That is a much stronger business model than relying on everyone else to stay optimistic.
So the real headline is not that house prices are collapsing. It is that easy gains are getting harder to rely on. For landlords, developers and borrowers, that is the moment to become more conservative on valuation and more disciplined on exit planning. In property, a slower market does not just change the mood. It changes what counts as a safe deal.

No comments:
Post a Comment